Bitcoin Halving Explained: What Actually Happens to Price?
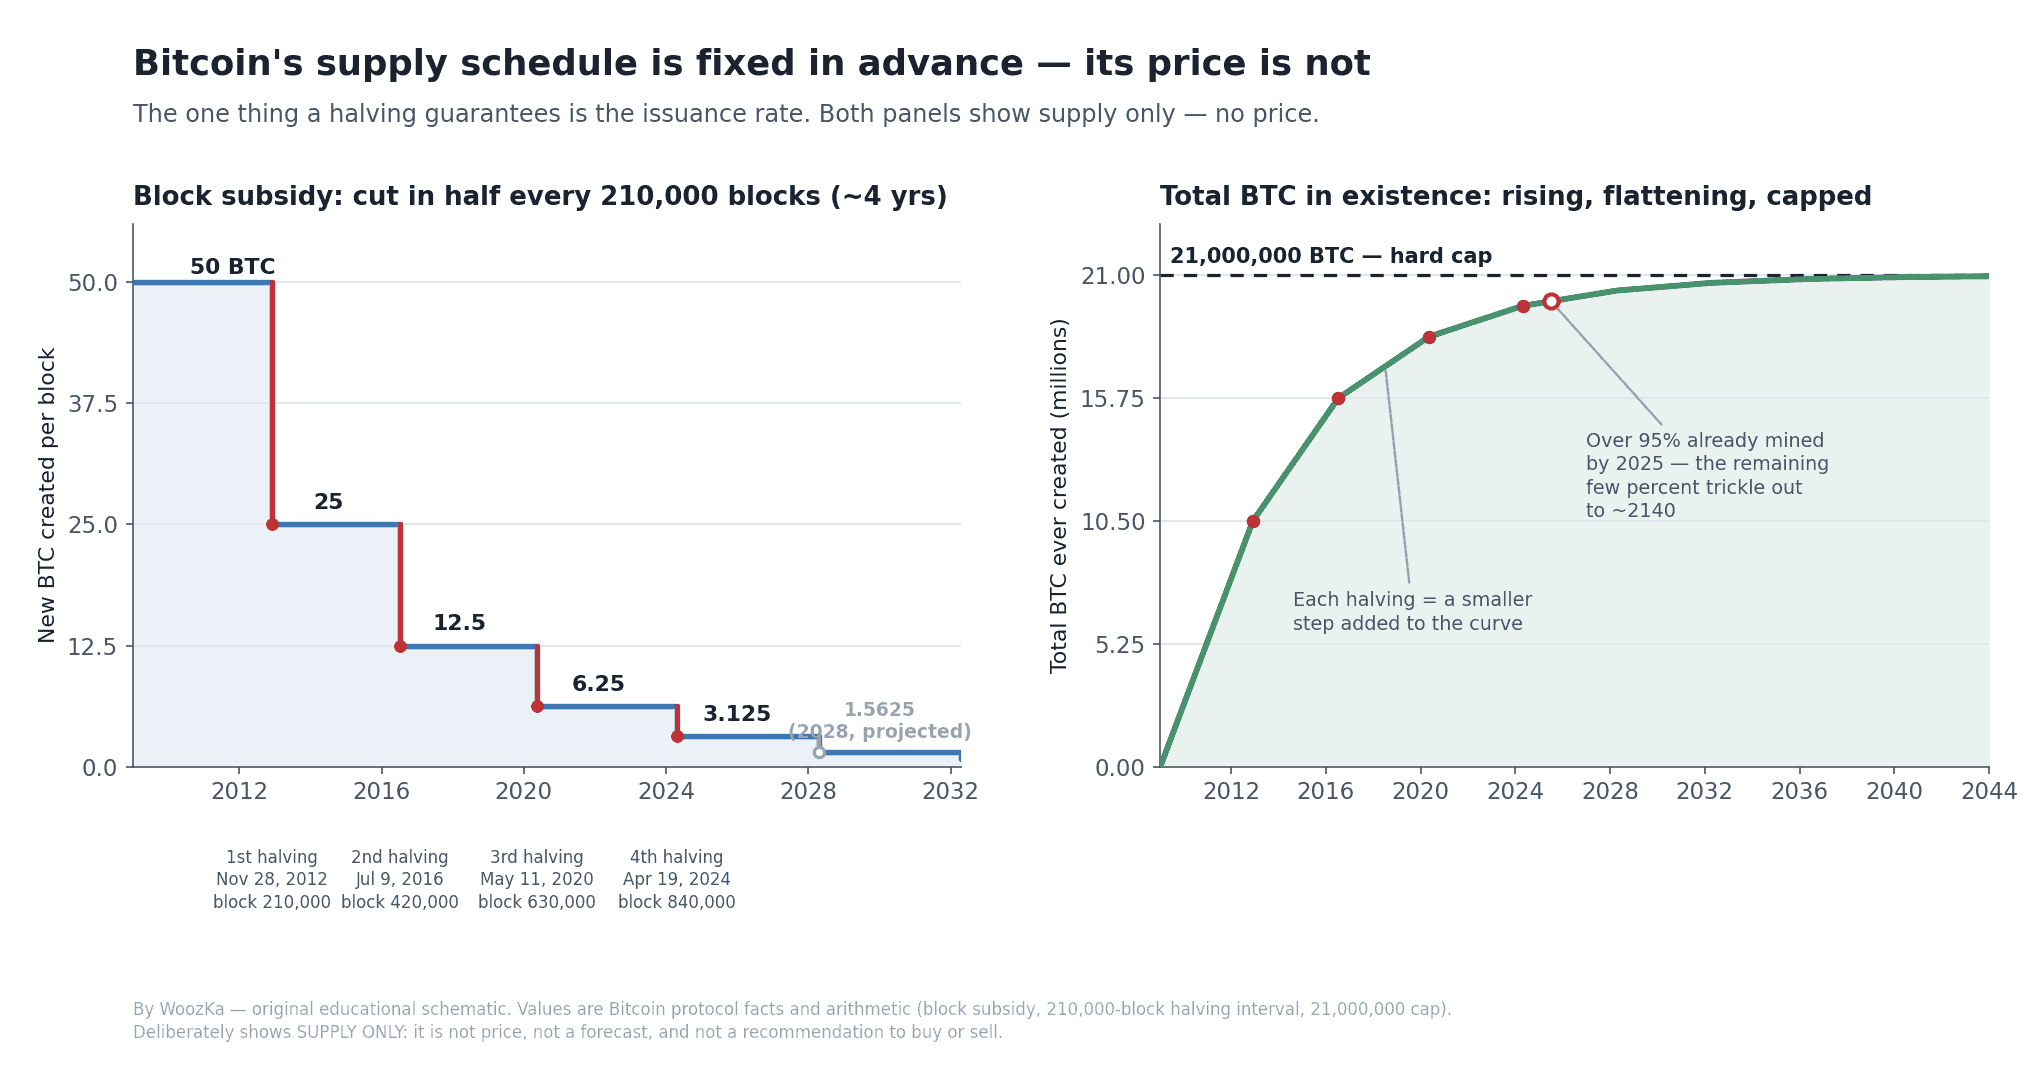
Two supply facts in one picture, and not a single price line. Left: the number of new bitcoins created per block is cut in half at each halving, on a schedule known years ahead. Right: because of that schedule, total supply rises, flattens, and is capped at 21 million. What the halving does to price is a separate — and far less certain — question, which is the whole subject of this article.
If you’ve read the pillar on buying your first Bitcoin safely, you know this silo’s rule: risk management first, price speculation last. The halving is where that rule gets tested, because “the halving” is the single most hyped event in crypto — the thing headlines, influencers, and countdown clocks insist will send the price to the moon. This article does something different. It explains exactly what a halving is (which is knowable and simple), and then looks honestly at what it does to price (which is neither).
One thing up front, because it frames everything below: Bitcoin is exceptionally volatile and can lose a large share — or in principle all — of its value. That isn’t a bearish take; it’s the explicit position of financial regulators. The U.S. Securities and Exchange Commission tells investors that “the only money you should put at risk with any speculative investment is money you can afford to lose entirely” [source: SEC / Investor.gov, “Exercise Caution with Crypto Asset Securities,” Mar. 23, 2023], and the U.K.’s Financial Conduct Authority puts it plainly: “if you invest in crypto, be prepared to lose all your money” [source: FCA, “Investing in crypto,” InvestSmart; FCA 2021 warning]. Nothing about a halving changes that. And to be equally plain about this article’s own limits: it makes no price prediction, none, anywhere — not a target, not a “best time to buy,” not a hint. History is described; the future is not forecast. This is educational content, not advice.
What a Halving Actually Is
Bitcoin pays the people who secure its network — miners — a reward for each block of transactions they add. That reward has two parts: a block subsidy (brand-new bitcoins created out of thin air by the protocol) plus the transaction fees users paid to be included. The block subsidy is the part the halving touches.
Roughly every four years — more precisely, every 210,000 blocks, at Bitcoin’s target of one block about every ten minutes — the protocol cuts the block subsidy exactly in half. That’s the whole event. It isn’t a vote, a decision, or a market reaction; it’s a line of code that has been in Bitcoin since the beginning, and everyone can see it coming years in advance. The subsidy started at 50 BTC per block in 2009 and has been halved four times, to 3.125 BTC today [source: Bitcoin protocol; block-subsidy schedule as documented across CoinMarketCap Academy, Kraken, and Bitbo halving records].
The important consequence is what it does to new supply. A halving doesn’t destroy any existing bitcoins or change anyone’s balance. It slows the rate at which new ones are created. After the 2024 halving, the network went from issuing roughly 900 new BTC per day to roughly 450 [source: reporting on the Apr. 2024 halving, e.g. LSEG and Bitcoin.com — daily issuance figures]. Same coins in circulation the day after as the day before; just a smaller trickle of new ones from then on.
The Four Halvings So Far
Here is the entire history, with dates and block heights — the facts a halving actually delivers:
| Halving | Date | Block height | Block subsidy (before → after) |
|---|---|---|---|
| 1st | Nov 28, 2012 | 210,000 | 50 → 25 BTC |
| 2nd | Jul 9, 2016 | 420,000 | 25 → 12.5 BTC |
| 3rd | May 11, 2020 | 630,000 | 12.5 → 6.25 BTC |
| 4th | Apr 19, 2024 | 840,000 | 6.25 → 3.125 BTC |
[source: halving dates and block heights per CoinMarketCap Academy, Kraken “History of Bitcoin halving,” and Bitbo halving records; block 630,000 was mined at 19:23 UTC on May 11, 2020; block 840,000 on April 19–20, 2024.]
The next halving is expected around April 2028 at block 1,050,000, when the subsidy will fall from 3.125 to 1.5625 BTC [source: projected from the 210,000-block interval; date estimates per CoinGecko/Bitbo halving countdowns — the exact date drifts with actual block times and can only be pinned down as it approaches]. Notice that the date is an estimate but the block is not: the halving happens at a fixed block number, and the calendar date simply follows from how fast blocks are found.
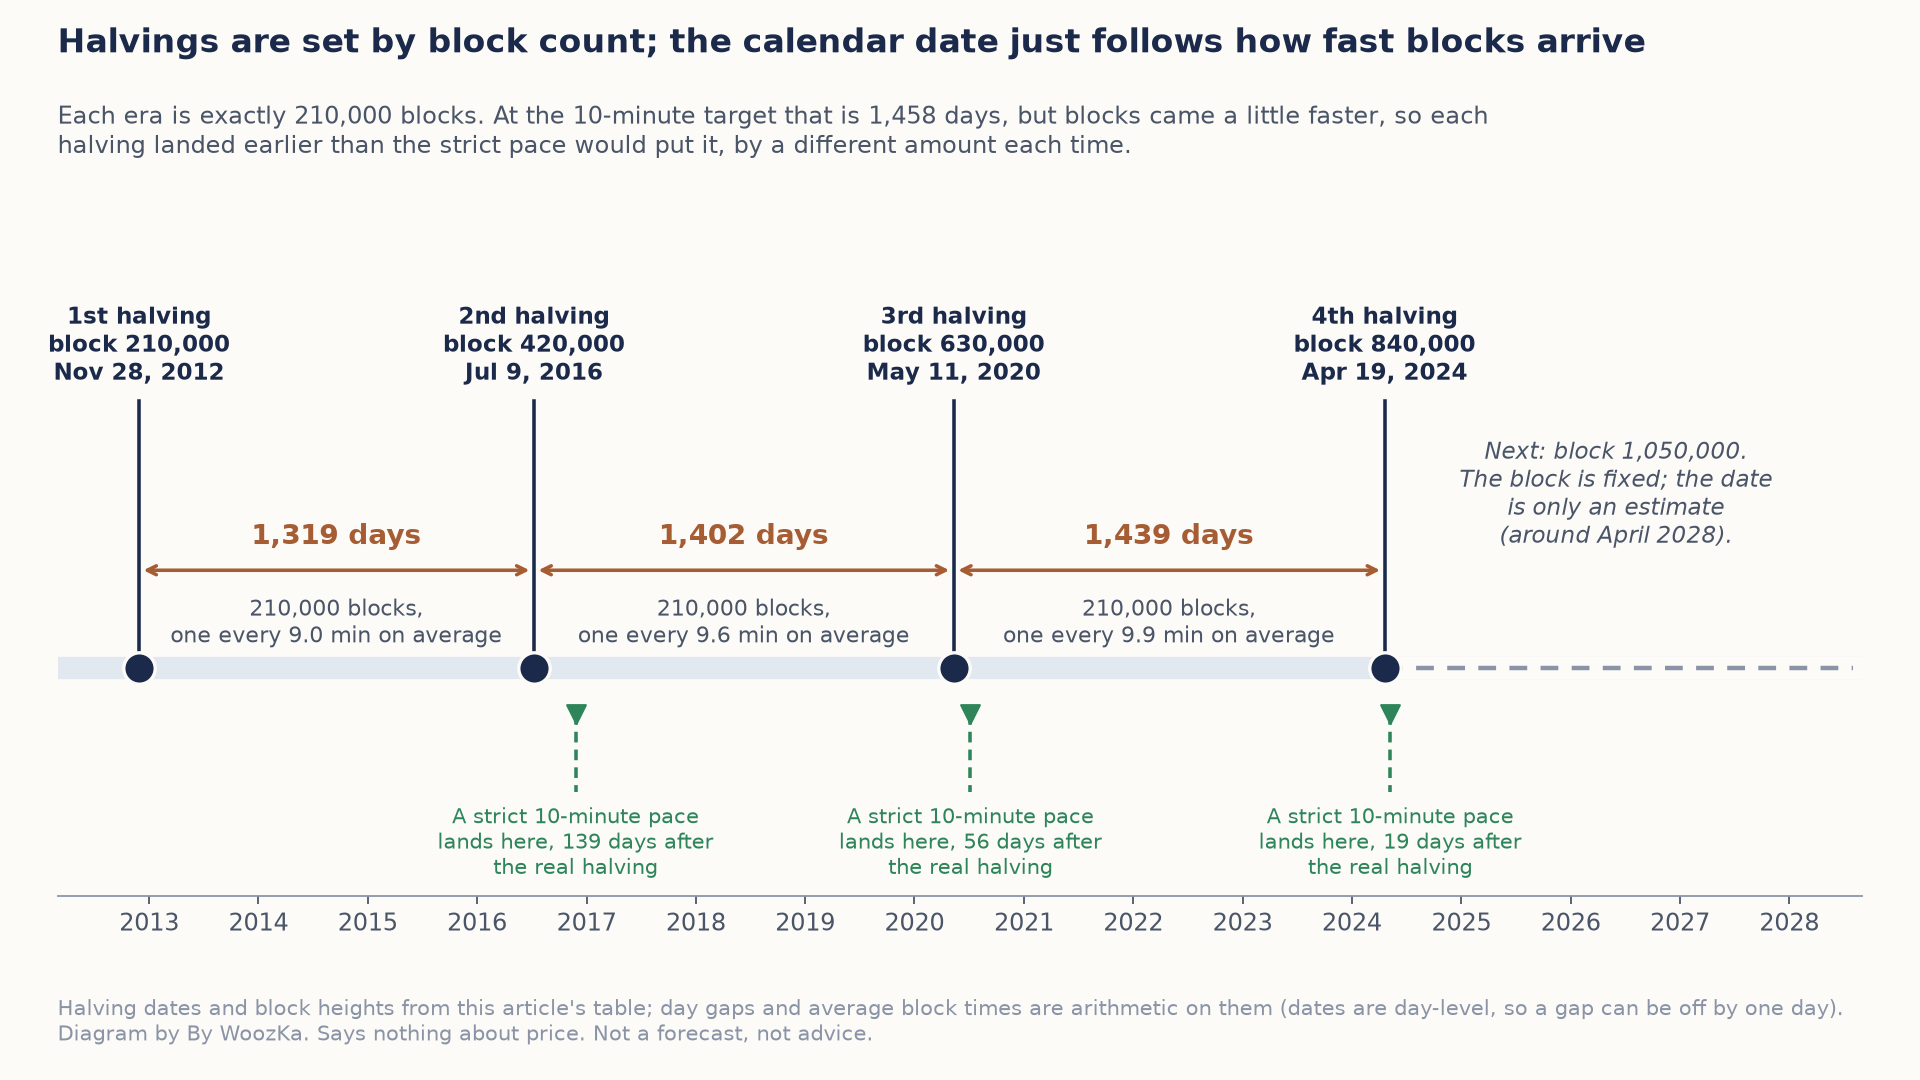
Every era is exactly 210,000 blocks, but blocks arrived a little faster than ten minutes, so each halving came earlier than the strict pace would put it. That is why the block is certain and the date is an estimate.
Why Halvings Exist: The 21 Million Cap
The halving isn’t arbitrary. It’s the mechanism that enforces Bitcoin’s most-cited property — a fixed maximum supply of 21 million coins, hard-coded by Satoshi Nakamoto in 2009 [source: Bitcoin protocol; The Block and CoinGecko explainers on the 21 million cap]. The math is worth seeing once, because it demystifies the whole thing. Each “era” of 210,000 blocks issues a subsidy that’s half the previous era’s, so the total ever created is:
210,000 blocks × (50 + 25 + 12.5 + 6.25 + …) BTC = 210,000 × 100 = 21,000,000 BTC
That’s a geometric series that sums to a finite number no matter how many halvings occur. The subsidy keeps halving toward zero but never quite reaches it, which is why the last fractions of a bitcoin are expected to be mined only around the year 2140 — even though over 95% of all bitcoin that will ever exist had already been mined by 2025 [source: The Block, “Bitcoin’s mined supply crosses 95% of 21 million cap,” 2025; CoinGecko, “What happens when all 21 million bitcoins are mined”]. The right-hand panel of the chart above is exactly this: a curve that rises fast, flattens, and stops at 21 million.
So the halving is the tool that turns “there will only ever be 21 million” from a slogan into a schedule. That part is genuinely certain. Everything after this point is where certainty ends.
What Actually Happens to Price? The Honest Answer
Here is the claim you’ll see everywhere: every halving has been followed by a huge bull market, so the next one will be too. The first half of that sentence is roughly true as history. The second half is a forecast dressed up as a fact — and it’s exactly the kind of reasoning this site won’t make for you.
Start with what history shows, stated as history:
- After the 2012 halving (BTC around $12), Bitcoin rose over the following year to roughly $1,150 by late 2013.
- After the 2016 halving (BTC around $650), it reached roughly $19,700 by December 2017.
- After the 2020 halving (BTC around $8,600), it reached roughly $69,000 by November 2021.
- After the 2024 halving (BTC around $64,000), it first traded above $100,000 in December 2024.
[source: approximate halving-day prices and subsequent cycle highs per CoinMarketCap Academy, Kraken, and Bitget halving-history compilations; figures describe historical price behavior only and are not a forecast.]
Read quickly, that looks like an iron law. Read carefully, it falls apart as a basis for prediction, for at least four reasons — and an honest answer has to give all four.
One: the sample is tiny. There have been four halvings, ever. Four data points is not a pattern you can lean money on; it’s an anecdote with a chart. Any “it always happens” claim about crypto is built on a sample most statisticians wouldn’t publish.
Two: the halvings didn’t happen in a vacuum. Each coincided with enormous, unrelated forces — waves of new adoption, the 2020–21 era of near-zero interest rates and pandemic stimulus, the arrival of futures markets, and in 2024 the launch of U.S. spot Bitcoin ETFs that pulled in tens of billions of dollars. When several big things move together, you cannot cleanly credit the price move to any one of them. Correlation is not causation, and here the correlation is tangled with half a dozen other candidates.
Three: the formal evidence is mixed, not settled. Researchers who’ve studied this can’t agree that halvings reliably move price. One 2024-era study using a synthetic-control method found a positive price effect around the 2024 halving but could not obtain a statistically significant, robust causal estimate for the 2020 halving — most likely because COVID-era market chaos drowned out any halving signal [source: academic work on estimating the halving’s price impact via synthetic control, 2024–2025; see also MDPI, “An Empirical Examination of Bitcoin’s Halving Effects,” 2024, and “Some stylized facts about Bitcoin halving,” ScienceDirect, 2024]. Different methods on the same handful of events reach different conclusions — which is itself the finding: the effect, if there is one, is not robust enough to bank on.
Four: the 2024 cycle already broke the script. In every prior cycle, Bitcoin set its all-time high after the halving. In 2024 it set a new all-time high near $73,000 in March — before the April halving — a first, widely attributed to spot-ETF demand rather than the supply cut [source: reporting on the March 2024 all-time high and April 2024 halving, e.g. CNBC and Forbes Advisor]. If the mechanical “halving then pump” story were the whole engine, the record wouldn’t keep arriving early. The pattern people treat as a law is already bending.
Put together, the honest answer to “what happens to price?” is: historically, big rallies have followed the first three halvings, but the sample is minuscule, the cause is confounded, the studies disagree, and the most recent cycle already departed from the template — so no one, including this article, can tell you what happens next.
“Is It Already Priced In?”
There’s a deeper reason to be skeptical of trading around a halving specifically: the event is the most predictable one in all of finance. The exact block, the exact new subsidy, and the approximate date are known years ahead. The efficient-market view says that anything this widely known should already be reflected in today’s price — markets don’t hand out free money for showing up to an event everyone had on their calendar [source: efficient-market framing applied to the halving, e.g. CoinDesk, “This Bitcoin Halving Is Different. But Is It ‘Priced In’?”, Apr. 2024].
Crypto markets aren’t perfectly efficient, and reasonable people argue about how fully the halving is discounted in advance. But the burden of proof runs the other way from the hype: if the halving’s supply effect is common knowledge, the naive plan of “buy because the halving is coming” is betting that the entire market somehow forgot to account for a date printed in the source code. That’s a weak foundation for risking money you can’t afford to lose.
The Stock-to-Flow Story, and Why It’s a Caution
No halving explainer is complete without stock-to-flow (S2F) — the model that fueled much of the “number go up” narrative. S2F takes the ratio of existing supply (“stock”) to annual new issuance (“flow”), which roughly doubles at each halving as flow is cut in half, and maps it to price. Through about 2020, the model’s line and Bitcoin’s price looked strikingly similar, and it developed a devoted following [source: PlanB, “Modeling Bitcoin Value with Scarcity,” and follow-ups, 2019–2020].
Then it failed. S2F projected prices for the 2021–2022 cycle that Bitcoin came nowhere near, and the model was widely criticized and largely abandoned as a forecasting tool [source: reporting and analysis on the stock-to-flow model’s post-2021 breakdown; general market commentary]. The core objection was there all along: S2F is a supply-side model that ignores demand entirely. Scarcity is not the same as value — an asset can be perfectly scarce and still be worth little if no one wants it. A fixed supply schedule tells you how many bitcoins exist; it tells you nothing about how many people will want them, at what price, next year.
The lesson for a beginner isn’t “here’s the right model instead.” It’s that a confident-looking curve that fit the past can miss the future badly, and that a model which reduces price to a single supply number is exactly the kind of thing to distrust — especially when it’s being used to sell you urgency.
What a Halving Actually Changes: Miner Economics
Where the halving’s effect is concrete and immediate is on miners. Overnight, the new-bitcoin half of their revenue is cut in half. Miners running older, less efficient machines or paying high electricity prices can be pushed below break-even, and some shut down. The network responds through its difficulty adjustment — as miners drop off, mining gets easier for those who remain, which helps the survivors stay viable [source: general Bitcoin mining mechanics; CCN and industry explainers on post-halving miner economics].
This matters for understanding Bitcoin’s long-run design, not for timing a trade. Today the subsidy still dwarfs fees — a 2024 block carried 3.125 BTC of subsidy against only a small fraction of a BTC in fees [source: The Block and industry reporting on subsidy-vs-fee revenue mix, 2024]. But every halving shifts the balance: the subsidy marches toward zero, and by design transaction fees must eventually pay for the network’s security on their own. Whether fees will be large enough to keep the network secure once the subsidy is negligible is a genuine open debate among serious people — an interesting question about Bitcoin’s distant future, and one nobody can resolve today.
The Supply Schedule, Actually Counted
The section above is the one place this article says the halving’s effect is “concrete and immediate” — and it is the only section on the page that prints no number at all. It makes three claims in a row: that miners lose half of something, that the subsidy still dwarfs fees, and that fees must eventually pay for the network on their own. All three are answerable from figures this page already publishes: the 210,000-block era, the 50 BTC opening subsidy, 3.125 BTC today, and a block about every ten minutes. Nothing below uses a price, and nothing below is a forecast.
Every Halving Mines Half of What Is Left
The geometric series above is written out once and then left as algebra. Running it era by era turns it into a ladder, and the ladder has a shape the series hides.
| Era | Subsidy | Mined in era | Total mined | Share of cap |
|---|---|---|---|---|
| 1st | 50 BTC | 10,500,000 | 10,500,000 | 50% |
| 2nd | 25 BTC | 5,250,000 | 15,750,000 | 75% |
| 3rd | 12.5 BTC | 2,625,000 | 18,375,000 | 87.5% |
| 4th | 6.25 BTC | 1,312,500 | 19,687,500 | 93.75% |
| 5th | 3.125 BTC | 656,250 | 20,343,750 | 96.875% |
| 6th | 1.5625 BTC | 328,125 | 20,671,875 | 98.4375% |
Every row mines exactly half of whatever was still outstanding when it began, so the total after the nth era is the cap less a half to the nth — 50%, 75%, 87.5%, 93.75%, and on. That single line explains the claim this page makes a paragraph earlier. Over 95% mined by 2025 is not a milestone that arrived in 2025; 93.75% was already mined the morning the 2024 halving landed. The remaining distance to 95% is 262,500 BTC, which is 84,000 blocks, which is about 583 days at the protocol’s nominal pace — late 2025, which is what the cited reporting found. The whole of the current era lives between 93.75% and 96.875%, so “95% mined” will be true and unremarkable for years, and the figure creeping toward 100 is a fact about the schedule rather than news about the network.
Why a Halving Is Not a Fifty-Percent Pay Cut
“The new-bitcoin half of their revenue is cut in half” is exactly right about the subsidy and says nothing about the paycheck, because the other half of a miner’s revenue is fees, and fees do not halve. Hold the fee take steady in BTC, vary only what share of the block reward it started as, and both numbers move.
| Fee share before | Revenue cut | Fee share after |
|---|---|---|
| 0% | 50.00% | 0.00% |
| 1% | 49.50% | 1.98% |
| 5% | 47.50% | 9.52% |
| 10% | 45.00% | 18.18% |
| 20% | 40.00% | 33.33% |
The full 50% cut is the zero-fee row and only the zero-fee row; every real block is somewhere below it. The right-hand column is the part worth keeping. A halving raises the fee share of miner revenue on its own, with no change in what anyone pays to transact. A network collecting 5% of block reward in fees is collecting 9.52% the instant the subsidy halves, and one at 20% jumps to 33.33%. Nobody sent a different transaction; the denominator shrank. The rise is always real and always less than a doubling, which means the drift toward a fee-funded network is partly automatic — and also that a chart of fee share stepping up at each halving is measuring the subsidy, not demand for block space.
When Fees Have to Carry the Network
This article puts “the subsidy marches toward zero” a few sentences from the year 2140, which reads as though the handover is 115 years out. Those are two different dates. The last fractions of a bitcoin do get mined around 2140; the subsidy stops being the larger number long before that. Hold fees flat in BTC per block and the crossing is a matter of counting halvings.
| If fees hold at | Halvings away | Era | Estimated |
|---|---|---|---|
| 0.03 BTC | 7 | 12th | 2052 |
| 0.10 BTC | 5 | 10th | 2044 |
| 0.30 BTC | 4 | 9th | 2040 |
| 1.00 BTC | 2 | 7th | 2032 |
The striking part is how little the assumption matters. Because the subsidy falls geometrically, the number of halvings to the crossing is a logarithm of the fee level, so a thirty-three-fold range of guesses about fees moves the answer by five halvings — about twenty years — and every one of them lands this century. You do not need to know what fees will be to know that the question this article calls a debate about Bitcoin’s distant future is a mid-century question, arriving roughly ninety years before the date printed beside it. That does not settle the debate, and nothing here says fees will or will not prove sufficient. It puts the debate on a calendar, which is the one thing the surrounding paragraph promises and does not supply.
Method and limits, so this can be checked rather than taken on trust. No calculator on this site computes a block subsidy, so nothing above comes from a shipped tool; every figure is arithmetic on the protocol rule and the numbers this article already publishes, computed in code and checked before publication, with the article’s own 210,000-block era, four halving dates and block heights, 50 BTC opening subsidy, 3.125 BTC today, 1.5625 BTC next, block 1,050,000, the 900-to-450 BTC per day change and the 21,000,000 series all asserted before anything else is allowed to print. Two limits are real and both cut the same way. Every calendar year above is an estimate at the nominal ten-minute pace, which this article itself flags: the block height is certain and the date is not, and because blocks have in practice arrived slightly faster than ten minutes, the true dates land a little earlier rather than later. And the fee column is held flat in BTC purely to isolate the subsidy; fee revenue is volatile, so the crossing rows are a way of reading how little the answer depends on that number, not a claim about what fees will be. One footnote for completeness: because the subsidy is paid in whole satoshis and the last ones round away, the true cap is 20,999,999.9769 BTC — 0.0231 short of the round figure everyone quotes, including this page.
What This Means for You
If you’re a beginner, the useful takeaways from the halving are almost the opposite of the hype:
- The certain part is the supply schedule, not the price. You can know, exactly, how issuance changes. You cannot know what price will do — and the halving’s fame is precisely what makes “trading the halving” a crowded, already-anticipated bet.
- Four confounded data points is not a strategy. “It pumped the last three times” is history worth understanding, not a signal worth risking rent on. The moment someone uses the halving to justify a price target or a deadline to buy, you’re being sold a forecast that the evidence doesn’t support.
- The risks don’t take a cycle off. Bitcoin’s volatility and total-loss risk are the same before, during, and after a halving. If you hold or buy any, the discipline is the same one from the rest of this silo: decide the amount when you’re calm, size it so a complete loss is survivable, and don’t let an event countdown talk you past that line.
The halving is a fascinating, elegant piece of monetary engineering — a predictable, transparent way to enforce a fixed supply. That’s genuinely worth understanding. Just don’t confuse understanding the mechanism with predicting the market. One is written in the code; the other isn’t written anywhere.
Where to Go Next
The halving is a supply story; these build out the risk-and-literacy picture around it:
- How to Buy Your First Bitcoin Safely: A Step-by-Step Guide — the pillar: the risk-first walkthrough everything in this silo plugs into.
- Crypto Position Sizing: How Much of Your Portfolio Should Be Crypto? — the discipline that keeps a halving-driven rally (or crash) from doing real damage.
- Crypto Wallets Explained: Hot vs Cold Storage for Beginners — if you hold across a cycle, where and how you hold it is the next decision.
If you want markets explained plainly — risk-first, never hyped, no price targets — that’s what the newsletter is for. Subscribe below.
Disclaimer: This article is educational content, not financial advice. I am not a licensed financial advisor, and nothing here is a recommendation to buy or sell any security or asset. Investing and trading involve risk, including the possible loss of the money you invest. Do your own research and consider consulting a licensed financial professional before making investment decisions. Read the full Disclaimer.
Historical and backtested results are hypothetical, carry inherent limitations, and do not guarantee future results. Figures were accurate to the best of my knowledge as of this article’s last-updated date and may have changed.
