How to Open Your First Brokerage Account: A Step-by-Step Walkthrough
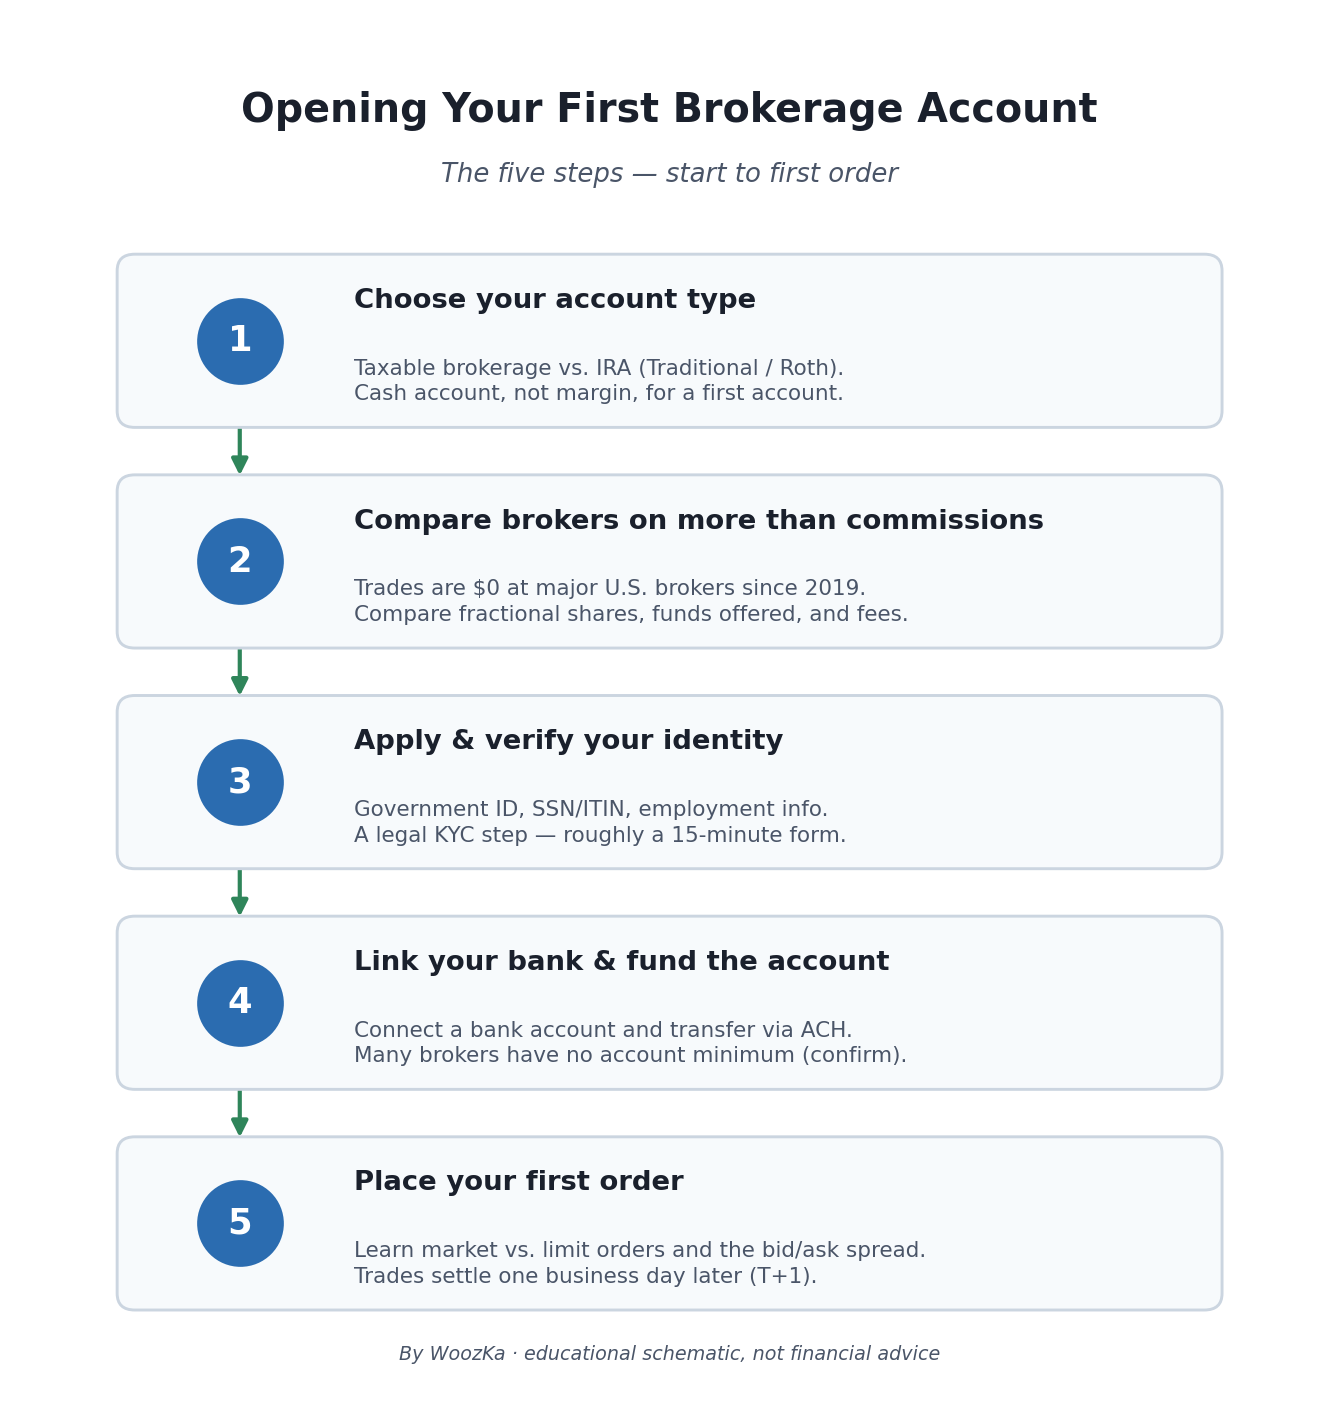
The whole process in one picture: pick an account type, compare brokers on more than just commissions, verify your identity, fund the account, and place a first order. Each step is explained below.
The mechanics of opening a brokerage account are genuinely easy — most applications take around 15 minutes and happen entirely online. If that’s a surprise, you’re not alone: the thing that actually keeps people from starting is not the paperwork, it’s the fog of unfamiliar terms sitting in front of the paperwork. Cash account or margin? Taxable or IRA? Market order or limit order? What is “settlement,” and is my money safe if the broker goes under?
This article clears that fog. It’s the foundational, on-ramp piece for the entire Stocks section of this blog — the one that assumes zero prior knowledge and walks you from “I’ve never done this” to “I’ve placed my first order and I understand what just happened.” One boundary up front, and it holds for everything below: this is a guide to account mechanics and basic literacy, not stock picking. Nothing here recommends a specific stock, and nothing here tells you a particular company is a good buy. That’s a line this blog doesn’t cross. What follows will get you set up and oriented; what to do once you’re set up is a longer education that the rest of the Stocks cluster is built to give you.
For most people, opening a first brokerage account is equal parts anticlimax and mild intimidation: the sign-up takes about fifteen minutes, and then you’re staring at an order screen full of unfamiliar terms — market, limit, shares, ticker — wondering what you’re even allowed to click. The thing worth knowing in advance is that the account itself is just a container; funding it and understanding the order types below is where the actual learning happens, and a first purchase can be small and boring on purpose.
First, What a Brokerage Account Actually Is
A brokerage account is simply an account, held at a licensed brokerage firm, that lets you buy and sell securities — stocks, ETFs, bonds, and so on. The broker is the intermediary that routes your order to the market and holds the securities you buy on your behalf. It is not a bank account, and that distinction matters more than it sounds.
Here’s the part worth internalizing before you fund anything. Reputable U.S. brokers are members of the Securities Investor Protection Corporation (SIPC). If a SIPC-member brokerage firm fails and customer assets go missing, SIPC protection covers you for up to $500,000 per customer — a total that includes a $250,000 limit for cash claims [source: SIPC, “What SIPC Protects,” sipc.org; U.S. SEC Investor.gov, “Investor Bulletin: SIPC Protection”]. But read what that protects against carefully: SIPC steps in when the firm fails, not when your investments fall in value. SIPC does not protect you against market losses. If you buy a stock and it drops 40%, that’s the market doing what markets do — no insurance covers it, and any product or person promising otherwise is not being honest with you. Bank-style FDIC insurance (which covers deposits up to $250,000 if a bank fails) is a different scheme for a different kind of account; some brokers sweep uninvested cash into FDIC-insured bank accounts, but your invested holdings are never FDIC-insured. Keep those two ideas — firm failure vs. market risk — cleanly separated in your head.
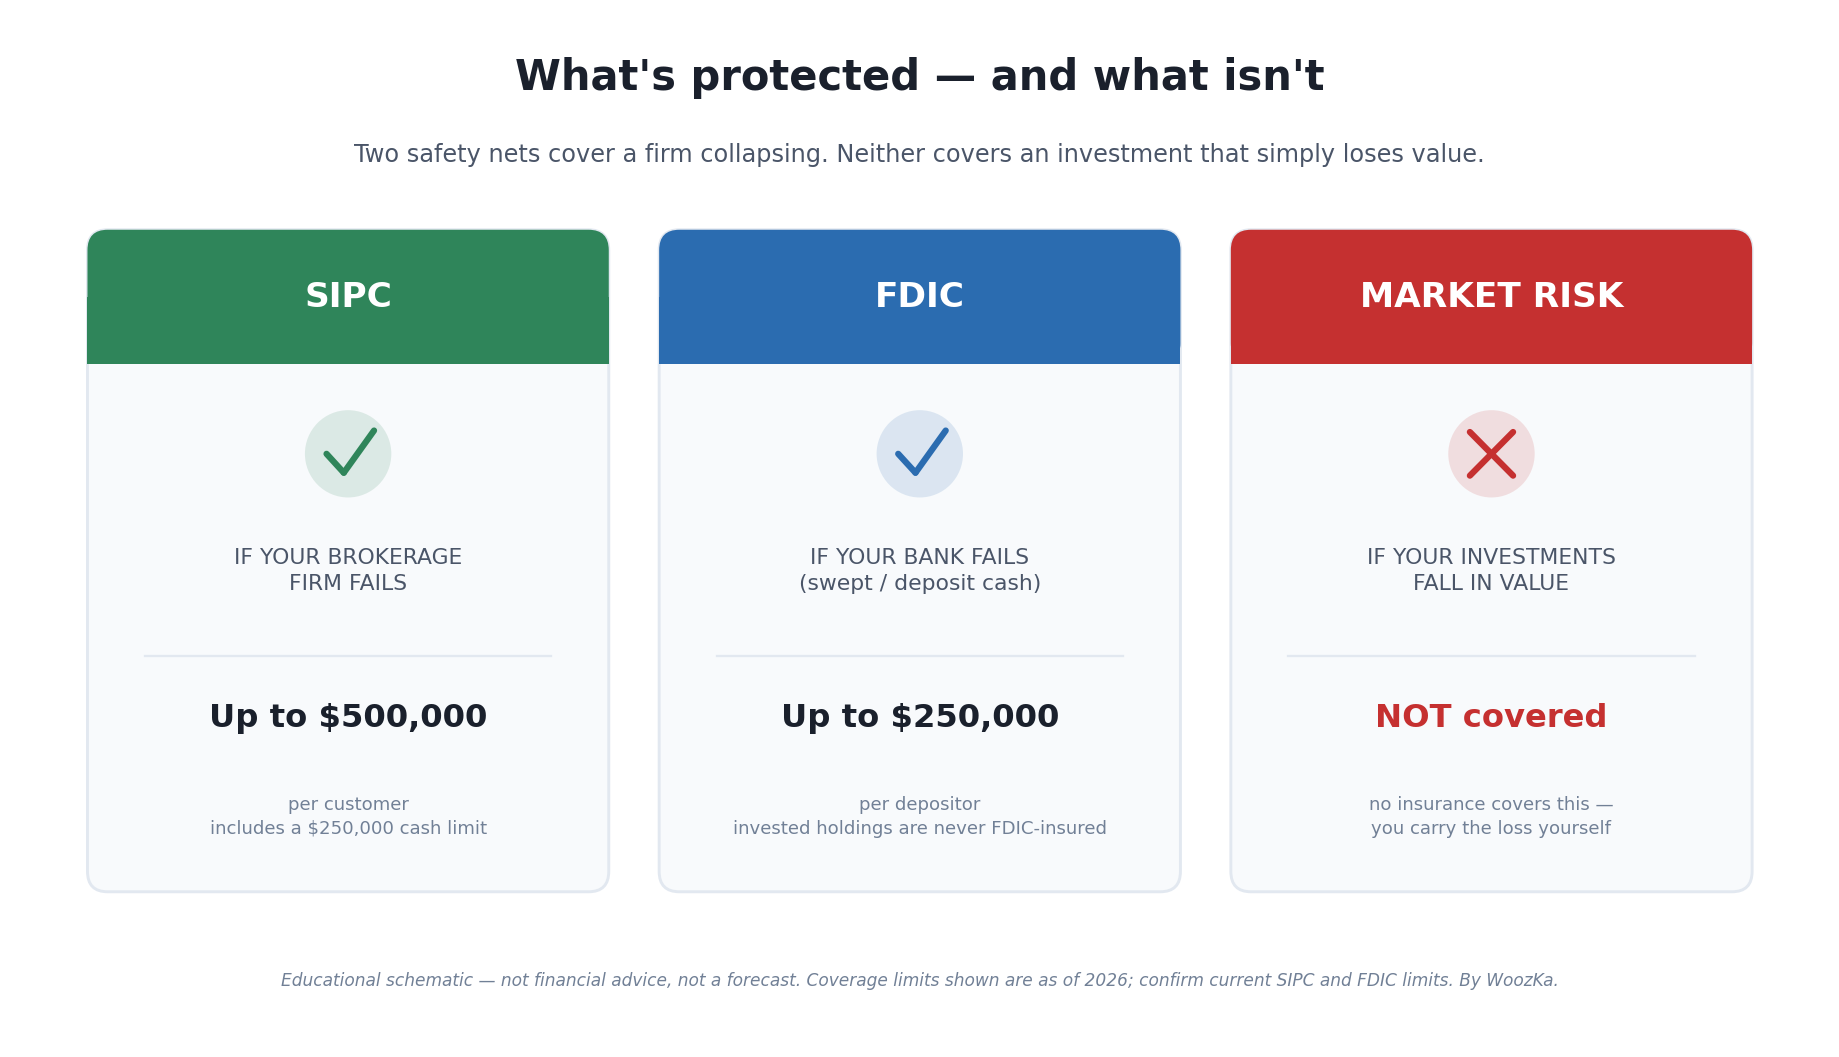
Two safety nets, one big gap. SIPC steps in if the brokerage firm fails; FDIC steps in if a bank fails. Neither insures an investment that simply drops in value — that risk is always yours. An educational schematic, not advice; coverage limits shown are as of 2026, so confirm the current SIPC and FDIC limits.
Before You Open: What You’ll Need
Opening an account triggers a legally required identity check. Under U.S. anti-money-laundering rules (the Customer Identification Program mandated by the USA PATRIOT Act), every brokerage must verify who you are before letting you trade [source: FINRA / U.S. Treasury FinCEN Customer Identification Program rules]. So have these ready:
- Your Social Security number or ITIN (for tax reporting — the broker files a 1099 with the IRS each year).
- A government-issued photo ID (driver’s license or passport).
- Basic personal and employment details — address, date of birth, employer, and some questions about your income and investing experience.
- A bank account to fund the new account, usually linked electronically.
None of this is unusual, and none of it obligates you to trade — it’s the same “know your customer” step a bank runs when you open a checking account. Set aside about 15 minutes.
Step 1 — Choose the Right Account Type
There are really two choices stacked on top of each other here, and beginners often conflate them.
Choice A: taxable brokerage account vs. tax-advantaged retirement account (IRA). A standard taxable brokerage account is the flexible, no-strings option — put money in, take it out whenever, invest in almost anything, and pay tax on dividends and on gains when you sell. An IRA (Individual Retirement Account) trades flexibility for tax advantages: a Traditional IRA generally gives you a tax break now and taxes withdrawals in retirement, while a Roth IRA is funded with after-tax money and lets qualified withdrawals come out tax-free later. The trade-off is access — IRAs are built for retirement, so pulling money out early can trigger taxes and penalties. IRAs also cap how much you can add each year: for 2026 the combined limit across your IRAs is $7,500, with an extra $1,100 catch-up contribution allowed if you’re 50 or older (so $8,600) [source: IRS, “401(k) limit increases to $24,500 for 2026, IRA limit increases to $7,500,” Nov. 2025]. Which wrapper fits depends on your goals, income, and tax situation — that’s a genuinely personal decision, and a good one to talk through with a tax professional rather than take from a blog.
Choice B: cash account vs. margin account. A cash account means you can only invest money you’ve actually deposited. A margin account lets you borrow money from the broker to buy more than your cash allows — which amplifies gains and losses, adds interest costs, and can force you to sell at the worst possible time if the account value drops (a “margin call”). For a first account, the boring answer is the right one: start with a cash account. Borrowed money is not a beginner’s tool, and you can always upgrade later once you understand exactly what leverage does to risk.
Step 2 — Choose a Broker (What to Compare, Not Which to Pick)
Here’s a fact that reshaped this entire decision: in early October 2019, Charles Schwab, TD Ameritrade, E*TRADE, and Fidelity all cut commissions on online U.S. stock and ETF trades to $0 within about two weeks of one another, and commission-free trading has been the industry standard ever since [source: CNBC and Kiplinger, Oct. 2019]. That’s liberating and a little disorienting: if trades are free almost everywhere, how do you compare brokers? Not on the headline “$0 commission,” which is now table stakes. Compare on the things that still differ:
- Fractional shares. Can you buy $25 of a $400 stock, or must you buy whole shares? For small, regular investing, fractional support matters a lot.
- What you can actually hold. Stocks and ETFs everywhere; but access to specific mutual funds, bonds, or other products varies.
- Account minimums. Many major brokers now open accounts with no minimum — but confirm, because this changes and varies by account type.
- The fees that didn’t go to zero. “Commission-free” is not “cost-free.” Watch for margin interest rates, mutual-fund expense ratios, account-transfer or wire fees, and how the broker makes money on order flow. These are small but real.
- Tools, research, and usability. The interface you’ll actually use, plus research, education, and customer support.
Because fees, minimums, and features change and differ by firm, treat any specific broker claim as something to verify on the broker’s own current pricing page before you rely on it. This blog keeps a separate, regularly updated comparison — “Best Online Brokers for Beginners” — for readers who want a like-for-like breakdown; that’s the right place for firm-by-firm specifics, and it carries an affiliate disclosure. This pillar’s job is to teach you what the criteria mean so that comparison is legible when you get there.
Step 3 — Apply and Verify Your Identity
With your documents ready, the application itself is a short online form: personal details, the identity information from the checklist above, and a few regulatory questions about your income, net worth, and investing experience. Answer honestly — those questions set your account’s permissions, and there’s no prize for overstating your experience. Most brokers verify your identity electronically in minutes; occasionally they’ll ask you to upload a photo of your ID if something can’t be matched automatically. That’s it — the “opening” is genuinely the easy part.
Step 4 — Link Your Bank and Fund the Account
Next you connect a bank account and move money in. The standard method is an ACH transfer — the same electronic bank-to-bank rail behind direct deposit and online bill pay — which is free at essentially every major broker. You link the bank (usually by logging into it through the broker’s interface or entering routing and account numbers), then request a transfer. First transfers commonly take a few business days to clear before the funds are investable; wire transfers are faster but may carry a fee. As noted above, many brokers have no account minimum, so you can start with a small amount — but confirm the current terms for the specific account you opened.
Step 5 — Place Your First Order
This is the step where a little vocabulary saves you from expensive confusion. When you go to buy, you’ll choose an order type. The two you need on day one:
- A market order buys (or sells) immediately at the best price currently available. Simple and fast — but in a fast-moving or thinly traded stock, the price you get can differ from the price you saw a second ago.
- A limit order buys only at a price you set or better. You trade the certainty of getting filled right now for control over the price you pay. For beginners buying into volatile names, a limit order is a useful habit — it prevents nasty surprises.
You’ll also encounter the bid/ask spread: the small gap between the highest price buyers are offering (the bid) and the lowest price sellers will accept (the ask). In large, heavily traded stocks and ETFs the spread is tiny; in obscure ones it can be a meaningful hidden cost. And if your broker supports it, you may be able to place a dollar-based order — “buy $50 of this” — which quietly buys a fractional share.
One more concept that trips people up: settlement. When you buy, the trade doesn’t finalize the instant you click. Since May 28, 2024, the U.S. standard settlement cycle has been “T+1” — the official transfer of securities and cash completes one business day after the trade date (it used to be two days, “T+2”) [source: U.S. SEC Office of Investor Education and Advocacy, “New ‘T+1’ Settlement Cycle,” Investor Bulletin, Mar. 2024; compliance date May 28, 2024]. In a cash account, this matters: proceeds from a sale aren’t fully “settled” and freely reusable until the next business day, and repeatedly buying and selling with unsettled cash can trigger “good-faith” or “freeriding” violations that get an account restricted. Trade with settled cash and this never becomes your problem.
A common first-order path looks like this: a beginner picks a broad, low-cost index ETF rather than a single stock, uses a limit order to stay in control of the price paid, and keeps the size small enough that the point is learning the mechanics, not making money. Early mistakes tend to be procedural rather than catastrophic — an accidental market order into a fast-moving open, or a ‘good-faith violation’ from buying with cash that hasn’t settled yet — which is exactly why starting small matters.
What Happens After You Buy
Once you own the security, your job shifts from “how do I do this” to “how do I not sabotage myself.” A few things to expect:
- Dividends (if the holding pays them) show up as cash in your account, and many brokers let you automatically reinvest them.
- Statements and tax forms arrive periodically; each January or February you’ll get a 1099 summarizing dividends and any sales, which you use at tax time. In a taxable account, selling at a gain is a taxable event; in an IRA it generally isn’t.
- Cost basis — what you paid — is tracked by the broker and determines your taxable gain or loss when you eventually sell.
And a note on the temptation to trade frequently, because the rules here just changed. For years, U.S. regulators enforced a “pattern day trader” rule that required a $25,000 minimum balance in a margin account for anyone making four or more day trades in five business days. That rule is going away: on April 14, 2026, the SEC approved FINRA’s amendments to Rule 4210 that eliminate the $25,000 minimum and the pattern-day-trader designation entirely, effective June 4, 2026, replacing them with real-time intraday margin requirements; eligible margin accounts above roughly $2,000 gain access to intraday buying power, and brokerages have until October 2027 to fully implement the change [source: Charles Schwab, “SEC Approves Scrapping $25,000 Day Trader Minimum,” Apr. 2026; FINRA]. That is worth knowing so an outdated figure doesn’t confuse you — but understand what it does not change: day trading on margin is still, in the regulators’ own framing and the brokers’ own disclosures, a high-risk activity that is generally unsuitable for beginners. This blog is about investing, not day trading, and lowering a balance threshold doesn’t lower the risk of trading with borrowed money.
Where the $500,000 Actually Stops
The protection limits appear near the top of this article as two numbers and a warning: SIPC up to $500,000 including a $250,000 limit for cash, FDIC up to $250,000, and neither one covering a security that simply falls in value. The warning is the important half and it is stated correctly. What the article never does is work out when either limit binds — and the answer is not what the headline numbers suggest, because the smaller number does most of the work.
The Same $500,000, Sorted Differently
Take one account at one firm, hold the total fixed at the SIPC ceiling, and change only how much of it is sitting in cash rather than in securities. Securities are simply the balance of the $500,000 in every row.
| Cash share | Cash | Protected | Not protected |
|---|---|---|---|
| 0% | $0 | $500,000 | $0 |
| 25% | $125,000 | $500,000 | $0 |
| 50% | $250,000 | $500,000 | $0 |
| 60% | $300,000 | $450,000 | $50,000 |
| 75% | $375,000 | $375,000 | $125,000 |
| 100% | $500,000 | $250,000 | $250,000 |
Same firm, same failure, same $500,000. Protection runs from $250,000 to $500,000 — a spread of exactly 2.00× — and the only thing that moved was the label on the money. Notice too that the sublimit is completely invisible until cash passes half the account, and then every further dollar of cash is an uncovered dollar.
That behavior generalizes into a rule worth carrying, because it is simpler than the table. For any account up to the ceiling, the uncovered amount is exactly the cash above $250,000 — securities do not enter the calculation at all. That identity holds across every combination checked on a 51×51 grid of accounts up to $500,000. The share at which coverage begins to fall is $250,000 divided by the account value, so it is 50% on a $500,000 account and 25% on a $1,000,000 one: the larger the account, the smaller the cash share that starts costing you.
Broker Versus Bank, by What You Actually Hold
The article sets SIPC and FDIC side by side and leaves the comparison at “a different scheme for a different kind of account.” Read quickly, $500,000 against $250,000 invites the conclusion that a broker protects twice as much. Split by what is being held, that conclusion survives in one row and dies in another.
| What you hold | At a broker | At a bank |
|---|---|---|
| Stocks, ETFs, bonds | $500,000 | — |
| A money market mutual fund | $500,000 | — |
| Uninvested cash from a sale | $250,000 | $250,000 |
| A bank deposit | — | $250,000 |
The 2.00× reading is true of securities only. On cash the two schemes are a tie at $250,000, so the sentence a beginner is most likely to take away — that money is twice as safe at a broker — is wrong about precisely the part of the account they are most likely to think of as safe.
The middle row is the one worth slowing down on, because it shows the sublimit is a rule about a classification rather than about liquidity. SIPC states that money market mutual funds, “often thought of as cash,” are protected as securities. So the same $400,000, at the same broker, on the same day, is protected in full when it sits in a money market fund and to $250,000 when it sits as uninvested cash from a sale — a difference of $150,000 turning on what the instrument is called, not on how fast you could spend it.
The Step 1 Choice, in Coverage Terms
Step 1 above frames the taxable-versus-IRA decision entirely as a tax question, which is how almost every version of this guide frames it. SIPC applies its limit per separate capacity, not per account, and its own published examples fix what that means: two accounts in the same name are combined, while an IRA and a Roth IRA are each protected separately. Holding the money constant at $1,000,000 and varying only the structure:
| How the same $1,000,000 sits at one firm | Capacities | SIPC ceiling |
|---|---|---|
| One taxable account | 1 | $500,000 |
| Two taxable accounts, one name | 1 | $500,000 |
| Taxable + traditional IRA | 2 | $1,000,000 |
| Taxable + traditional IRA + Roth IRA | 3 | $1,500,000 |
Opening a second account in your own name at the same firm adds $0 of protection — a result that surprises most people, and the reason “spread it across accounts” is not the safeguard it sounds like. Moving the same money into a different capacity doubles the ceiling. Both results come straight from SIPC’s worked examples and neither depends on an estimate.
The honest counterweight belongs here rather than in a footnote. This arithmetic only ever matters if the firm fails and customer assets are missing, which is rare and is not something any of these numbers make more or less likely. Coverage is not a return, it does not reduce the risk of what you own, and treating it as a reason to arrange an account one way rather than another would be optimizing for the least likely thing in this article. The useful takeaway is narrower and it is the one the next section leads with: knowing which risk each scheme answers, so that neither number is mistaken for a promise about your investments.
Deriving the coverage figures: the sources used, and what they leave out. Every figure above is arithmetic on the two limits this article already publishes and sources, combined with the coverage rules read directly from the primary sources it cites — SIPC’s “What SIPC Protects” and “Investors with Multiple Accounts” pages, the SEC’s Investor.gov entry on SIPC, and the FDIC’s own deposit-insurance page, each read and title-checked on September 6, 2026. The calculation behind the tables reproduces SIPC’s five published examples as a control and checks every value before it is reported. None of the site’s calculators computes an insurance limit, so none is linked here. Coverage is modeled for one customer at one SIPC-member firm and ignores the additional excess-of-SIPC private insurance many brokers carry, which varies by firm and would only raise these figures; commodity futures and foreign-exchange positions, which SIPC does not protect, are outside the scope of this article and of these tables. The article’s own arithmetic was recomputed and confirmed: the 2026 IRA limit of $7,500 plus the $1,100 catch-up is exactly $8,600. Nothing above forecasts anything, recommends any account structure, broker, or security, or reports any personal experience; every figure is a consequence of published rules.
Common Beginner Mistakes to Sidestep
- Confusing “the broker is safe” with “my investments are safe.” SIPC covers firm failure, not market losses. Owning through a solid broker doesn’t reduce the risk of what you own.
- Reaching for margin early. Borrowed money magnifies losses and can force sales at the bottom. Start in a cash account.
- Buying something because it’s being talked about. A rising price and a loud crowd are not analysis. Understanding what you own and why is the whole game — and it’s a skill the rest of this cluster is built to teach.
- Ignoring the small stuff. Fund expense ratios, margin interest, and bid/ask spreads are quiet, recurring costs that compound against you over decades.
Where to Go Next
You now have an account and you understand the machinery around it. The next layer is literacy — learning to read what you’re actually buying:
- What Is a P/E Ratio and How Do You Actually Use It? — the most misused number in investing, explained as a tool, not a verdict.
- Growth vs. Value Investing: Which Approach Fits Your Goals? — two broad philosophies and how to think about which suits you.
- How to Read an Earnings Report Without an MBA — what companies actually disclose four times a year, in plain English.
- Dividend Investing 101: Building an Income Stream From Stocks — how dividends work and where they fit.
- The Difference Between Trading and Investing (And Why It Matters) — the mindset distinction that shapes every decision above.
If you’d like the plain-English read on markets and investing literacy delivered regularly — explained, never hyped — that’s what the newsletter is for. Subscribe below.
Disclaimer: This article is educational content, not financial advice. I am not a licensed financial advisor, and nothing here is a recommendation to buy or sell any security or asset. Investing and trading involve risk, including the possible loss of the money you invest. Do your own research and consider consulting a licensed financial professional before making investment decisions. Read the full Disclaimer.
