DeFi Explained: What Decentralized Finance Actually Means
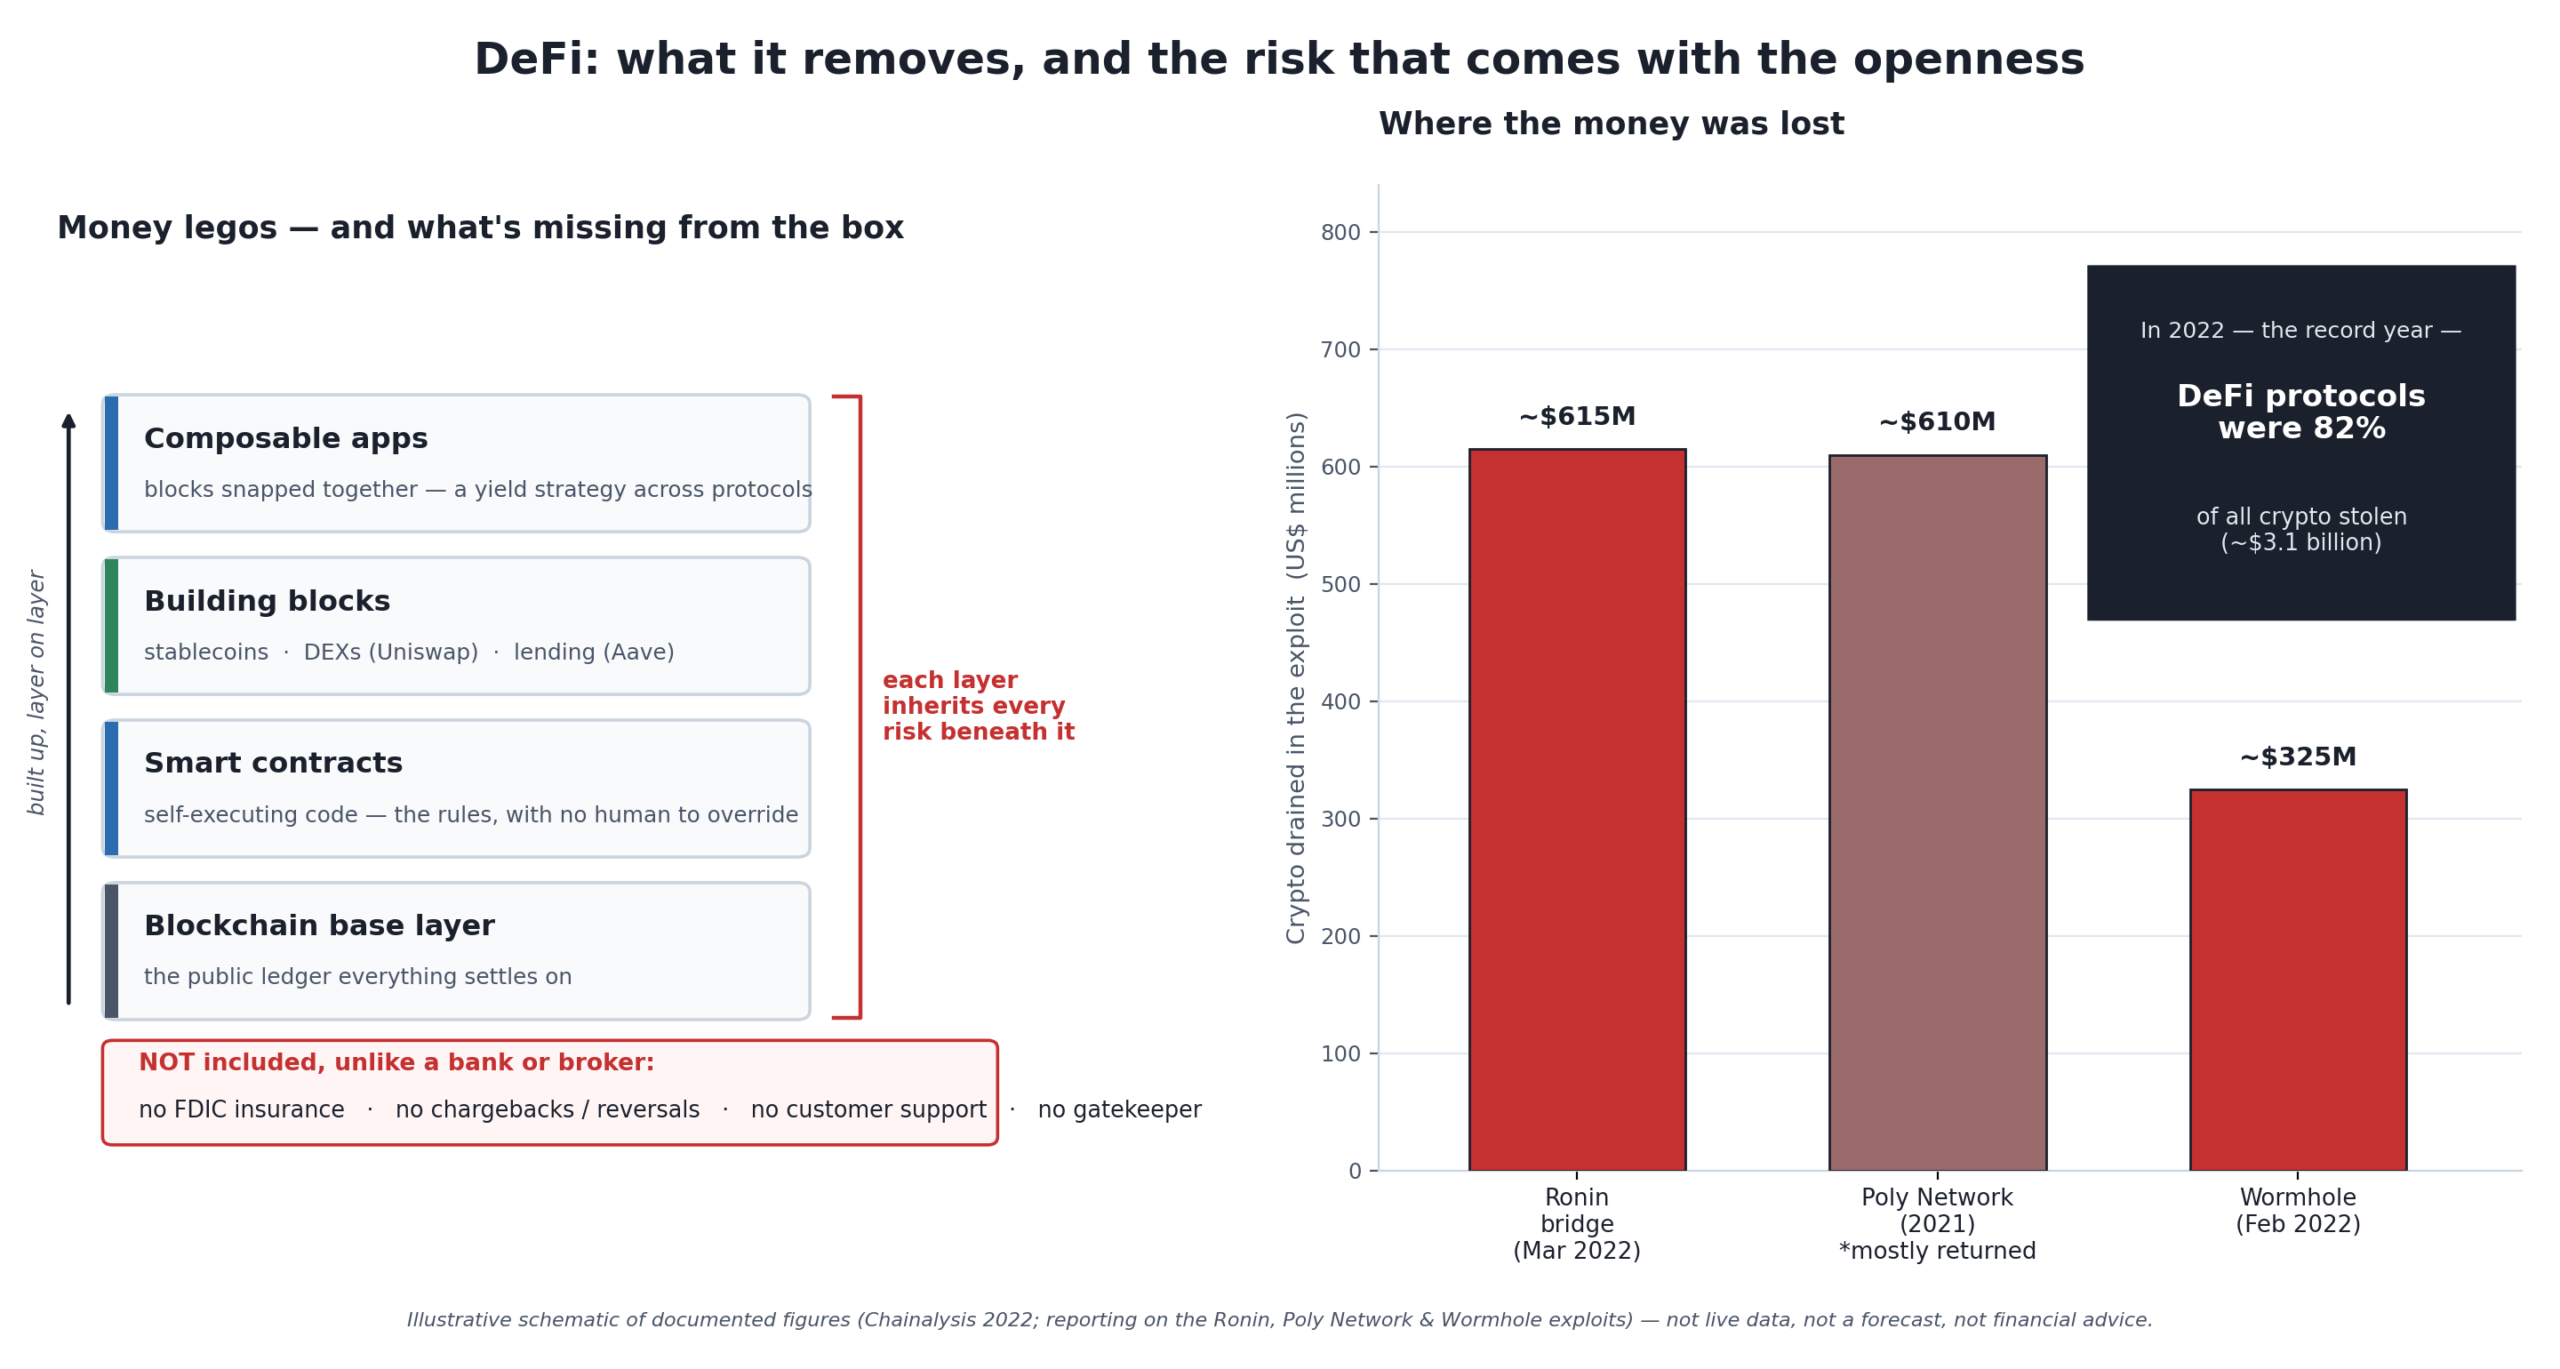
The whole article in one picture. Left: DeFi is a stack of open financial building blocks anyone can plug together — powerful, and missing the safety features the middleman used to provide. Right: those missing features are not abstract. When the code fails, there is no one to call and, usually, no money back.
If you’ve read the pillar on buying your first Bitcoin safely, you know this silo’s rule: risk management first, price speculation last. DeFi is where that rule gets tested hardest, because DeFi is genuinely impressive engineering wrapped around genuinely dangerous defaults. The pitch is seductive — earn double-digit yields, trade any token at 3 a.m., borrow without a credit check, all without a bank taking a cut or telling you no. Some of that is real. What the pitch leaves out is that removing the bank also removes everything the bank was quietly doing for you: insuring your deposit, reversing a fraudulent charge, freezing a stolen account, answering the phone when something breaks.
One thing up front, because it frames everything below: in DeFi, there is usually no one to make you whole. A US bank deposit is insured up to $250,000 by the FDIC; funds in a DeFi protocol are not insured by anyone [source: FDIC deposit-insurance basics; DeFi protocols carry no deposit insurance]. If a smart contract is exploited, if you approve a malicious transaction, or if a project’s developers vanish with the money, the transaction is typically final and irreversible — “code is law” cuts both ways. The U.S. Securities and Exchange Commission’s blanket caution about crypto applies with extra force here — “the only money you should put at risk with any speculative investment is money you can afford to lose entirely” — and the U.K.’s Financial Conduct Authority is blunter still: “if you invest in crypto, be prepared to lose all your money” [source: SEC / Investor.gov, “Exercise Caution with Crypto Asset Securities,” Mar. 23, 2023; FCA, “Investing in crypto,” 2021]. This article makes no price prediction and no recommendation — not which protocol to use, not whether to use any. It explains what DeFi actually is, the pieces it’s built from, how big it really is, and — most important — the specific ways it can cost you money. That knowledge is the safety equipment; it is not a green light.
What traditional finance includes that DeFi does not: no FDIC insurance, no chargebacks or reversals, no customer support, and no gatekeeper to stop a bad actor. Each layer also inherits every risk beneath it.
| Landmark bridge exploit | Amount |
|---|---|
| Ronin | ~$615 million |
| Poly Network | ~$610 million (later mostly returned) |
| Wormhole | ~$325 million |
In 2022, DeFi protocols accounted for 82% of all crypto stolen by hackers — about $3.1 billion.
What DeFi Actually Is
DeFi — short for decentralized finance — is a financial system built on public blockchains that aims to provide services like trading, lending, and borrowing without banks, brokers, or other intermediaries in the middle [source: Chainalysis, “What Is DeFi?” glossary]. Where a traditional transaction routes through a company that holds your money and enforces the rules, a DeFi transaction is executed by a smart contract — a program that lives on the blockchain and runs automatically when its conditions are met [source: Chainalysis; general definition]. The Ethereum blockchain popularized programmable smart contracts, and that programmability is what made DeFi possible: instead of a bank’s servers deciding whether your loan clears, open code does, and anyone can read that code.
A few properties follow from that design, and each is a double-edged sword:
- Permissionless. There’s no application, no gatekeeper, no approval process. Anyone with a crypto wallet can use most DeFi protocols. That’s a genuine opening for people traditional finance shuts out — and it also means there’s no gatekeeper standing between you and a scam, either.
- Non-custodial. You typically keep your assets in your own wallet and interact with the protocol directly, rather than depositing them with a company. You’re not trusting a firm to hold your money — but that means you, not a company, are responsible if something goes wrong. (The custody tradeoffs are the whole subject of the wallets article.)
- On-chain and transparent. The code and the transactions are public. You can, in principle, inspect exactly how a protocol works — a real advantage over an opaque bank. In practice, most users can’t read the code, so “transparent” often means “auditable by experts you’re implicitly trusting.”
- Always on. No market hours, no bank holidays, no borders. Convenient — and a reason mistakes happen fast, at 3 a.m., with no one to catch them.
The honest one-sentence version: DeFi replaces the trusted middleman with code, which is powerful precisely because it removes human discretion — and dangerous for exactly the same reason.
The Building Blocks: “Money Legos”
DeFi’s most-used metaphor is “money legos.” Each protocol does one financial job, and because they all run on the same blockchain and can call each other’s code, they snap together into more complex arrangements. This property is called composability, and it’s the source of both DeFi’s creativity and a lot of its fragility [source: Chainalysis; academic DeFi taxonomy]. A few core blocks are worth knowing by name.
Decentralized exchanges (DEXs). These let you swap one token for another straight from your wallet, with no company holding your funds in between. The dominant design is the automated market maker (AMM): instead of matching buyers and sellers through an order book, the exchange uses liquidity pools — piles of two tokens supplied by other users — and a formula sets the price based on the ratio in the pool. Uniswap is the largest DEX by volume and the canonical example; anyone can list a token on it without approval [source: Chainalysis; Uniswap AMM model]. Across the whole ecosystem, DEXs were handling on the order of $7 billion of trading volume a day in mid-2026 [source: DefiLlama industry metrics, June 2026 — DEX volume moves daily; this is a June 2026 reading, not a running total].
Lending protocols. Platforms like Aave and Compound let users supply crypto to a pool to earn interest, or borrow against collateral — with no credit check and no identity verification, because there’s no human underwriter, only code. The catch that trips up beginners: DeFi loans are almost always overcollateralized. To borrow $100, you might have to lock up $150 or more of another crypto asset, because the protocol’s only protection against default is collateral it can automatically seize and sell [source: Aave documentation; DeFi lending mechanics]. Aave also pioneered the flash loan — an uncollateralized loan that must be borrowed and repaid inside a single blockchain transaction — which is a clever tool for developers and, as we’ll see, also a favorite instrument of attackers.
Stablecoins. The dollar-pegged tokens that serve as DeFi’s “cash” — the thing you price trades against and park value in between moves. They’re important enough (and risky enough) to have their own article: Stablecoins Explained: How They (Try To) Hold Their Peg. For DeFi, the key point is that stablecoins are the connective tissue almost every other block relies on.
Yield farming and liquidity providing. When you supply your tokens to a liquidity pool or lending market, you earn a cut of the fees and, often, bonus tokens the protocol hands out to attract capital. Chasing the highest of these returns across protocols is called yield farming [source: Kraken Learn, “Yield Farming Explained”]. It’s where the eye-popping advertised percentages live — and, not coincidentally, where a lot of the risk in this article concentrates.
Put those together and you can see the appeal and the hazard at once. You can supply an asset to a lending pool, borrow a stablecoin against it, swap that stablecoin on a DEX, and deposit the result into a third protocol for yield — all in minutes, all without asking anyone. That’s the “money legos” dream. It’s also four separate smart contracts that each have to work perfectly, stacked on top of each other, with your money threaded through all of them.
How Big Is DeFi, Really?
It’s easy to get the scale wrong in both directions. The number the industry watches is total value locked (TVL) — the total worth of all the crypto currently deposited in DeFi protocols. As of mid-2026, DeFi TVL was roughly $72 billion, down about 37% since the start of the year, when it stood near $114 billion [source: DefiLlama, June 2026]. Ethereum still hosts a slim majority — about 53% of all DeFi TVL — with the rest spread across Solana and dozens of other chains [source: DefiLlama, 2026]. The single largest protocol, the lending market Aave, held on the order of $26 billion on its own [source: DefiLlama protocol rankings, 2026].
Two pieces of context keep that number honest. First, TVL is volatile — it swings with both crypto prices and how much yield-chasing capital is around, which is exactly why it can fall by more than a third in a few months without any single disaster. It is a thermometer for enthusiasm as much as a measure of size. Second, DeFi is still small next to the rest of crypto, let alone traditional finance. The total supply of stablecoins alone was around $314 billion in mid-2026 — more than four times all of DeFi TVL — and both figures are rounding errors beside the tens of trillions in the conventional banking and securities system [source: DefiLlama, June 2026]. DeFi is an important, fast-moving experiment. It is not yet a pillar of the financial world, and treating it like a settled, safe institution is the core mistake this article is trying to prevent.
The Risks the Openness Creates
This is the section that matters. Everything attractive about DeFi — permissionless, non-custodial, composable, unstoppable — has a shadow, and beginners lose money in the shadow. Here are the main ones, in rough order of how much damage they’ve done.
Smart-contract risk: the code can be broken, and there’s no undo
A smart contract is only as safe as the code it’s made of, and DeFi code manages enormous sums in public view — a standing invitation to attackers. The numbers are not small. 2022 was the biggest year ever for crypto hacking, with about $3.8 billion stolen, and DeFi protocols were the victims in 82.1% of it — roughly $3.1 billion [source: Chainalysis, “2022 Biggest Year Ever for Crypto Hacking,” Feb. 2023]. The most spectacular failures were cross-chain bridges, the plumbing that moves assets between blockchains: the Ronin bridge lost about $615 million in March 2022 (later attributed to North Korea’s Lazarus Group), Poly Network lost about $610 million in 2021 (unusually, the attacker returned nearly all of it), and Wormhole lost about $325 million in February 2022 [source: bank-info and blockchain-security reporting on the Ronin, Poly Network, and Wormhole exploits, 2021–2022; Elliptic]. Many of these attacks use the flash loans mentioned earlier — borrowing a fortune with no collateral, using it to manipulate a protocol inside a single transaction, and pocketing the difference.
There is a genuine bright spot worth stating plainly: as security practices, audits, and monitoring have improved, DeFi-specific hack losses moderated in 2024 and 2025 even as more value flowed in — a sign the field is learning [source: Chainalysis crypto-hacking reports, 2024–2026]. But “improving” is not “solved” — total crypto theft still ran into the billions each year. The durable lesson is structural: when a DeFi contract is drained, the transaction is typically final. There is no FDIC, no fraud department, no chargeback, and usually no way to claw the money back. In traditional finance, a bad transaction can often be reversed. In DeFi, “code is law” means the exploit is as valid as any other transaction the moment it clears.
Impermanent loss: the risk that’s easy to not even know you’re taking
This one is counterintuitive, which is exactly why it catches people. When you supply two tokens to a liquidity pool to earn fees, and the two tokens’ prices move apart, the automatic rebalancing inside the pool can leave you with less value than if you’d simply held the two tokens in your wallet. That gap is called impermanent loss, and it’s the primary risk every liquidity provider takes [source: Chainlink, “Understanding Impermanent Loss”; dcentralab]. The math is unforgiving as prices diverge: a price ratio change of 1.25x produces about a 0.6% loss, 1.5x about 2%, and a 5x move about a 25.5% loss versus just holding [source: standard impermanent-loss formula; return.finance / Tangem, 2025]. The advertised “yield” on a pool has to beat this drag before you’re actually ahead — and the flashy percentages you see quoted rarely mention it. Pools of two closely-pegged assets (say two dollar-stablecoins) suffer far less of it, which is part of why they’re popular, but “less” is not “none.”
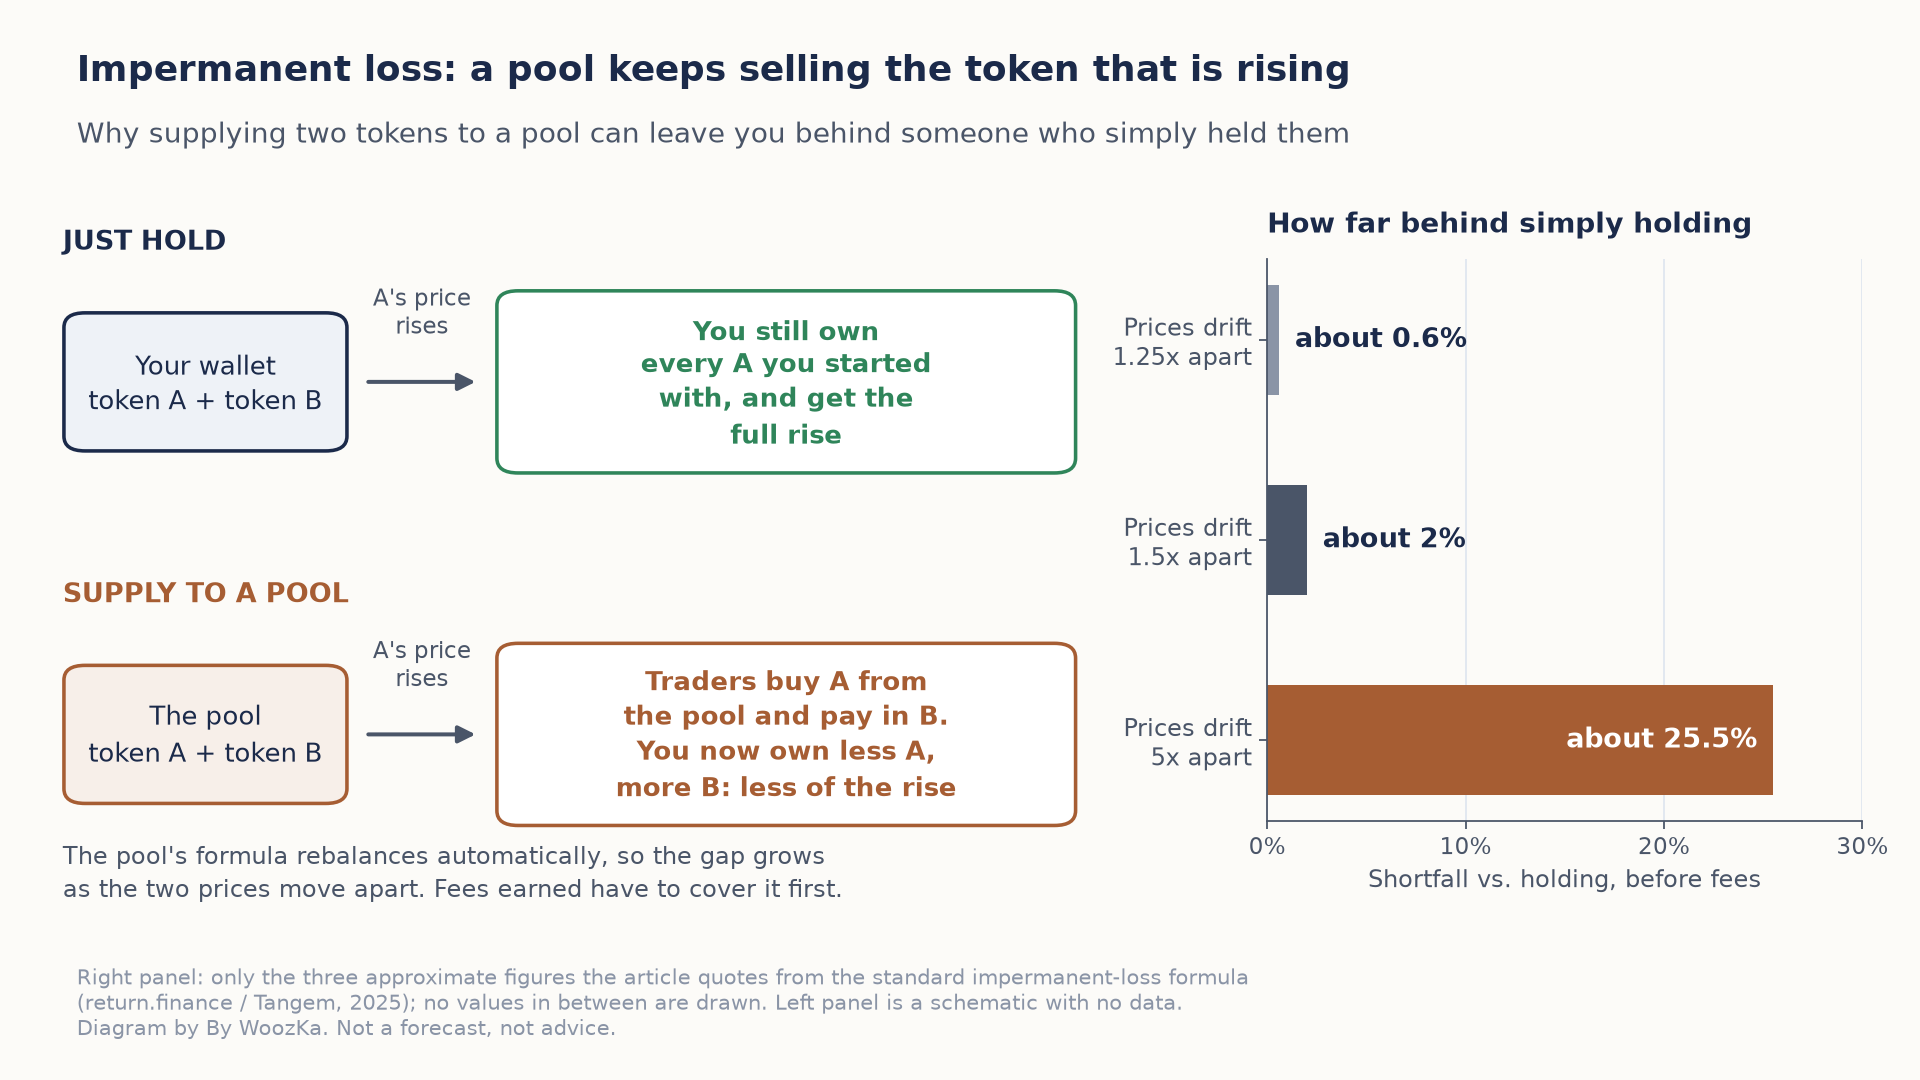
When one token in a pool rises, traders buy it out of the pool, so the provider ends up holding less of the winner than someone who simply held both tokens. The shortfall is small for small moves and grows quickly: about 0.6% at 1.25x, about 2% at 1.5x, and about 25.5% at 5x, before any fees earned.
Rug pulls and scams: the gatekeeper you removed was also stopping this
Because listing a token or launching a protocol is permissionless, so is launching a fake one. In a rug pull, developers create a plausible-looking project, attract deposits into its liquidity pool, and then drain the pool and disappear [source: DeFi risk taxonomy; ChainScore glossary]. There’s no exchange compliance desk to have caught them and no regulator who pre-approved the listing — the same openness that lets a legitimate builder ship without gatekeepers lets a thief do the same. Distinguishing the two before you deposit is genuinely hard, which is why the common crypto scams article exists; the DeFi-specific version is that a slick interface and a high advertised APY are not evidence of safety, and “audited” is a claim to verify, not a guarantee to trust.
No safety net, by design
It’s worth stating the theme directly rather than leaving it implied across the sections above. In DeFi there is no deposit insurance, no chargebacks, no account recovery, and usually no customer support. You are your own bank, which sounds liberating until the day you’d have wanted a bank. Send funds to the wrong address, approve a malicious contract, lose your keys, or deposit into a protocol that gets exploited, and the ordinary result is that the money is simply gone. This isn’t a bug the space is about to fix; it’s a direct consequence of removing the intermediary. The freedom and the exposure are the same coin.
“Yield” is not free money
Finally, treat a high advertised return as a risk signal, not a reward signal. A protocol offering double-digit or triple-digit “APY” is almost never printing money — that yield is coming from somewhere: from newly issued governance tokens that can lose value as fast as they’re earned, from other users’ trading fees and liquidation penalties, or from you unknowingly taking on impermanent loss, smart-contract risk, and counterparty risk. The same logic from the stablecoin article applies here in bold: any yield above what safe, boring assets pay is compensation for a risk you are taking, whether or not the interface tells you what it is. If you can’t name the risk behind a return, that doesn’t mean it’s absent — it means you haven’t found it yet.
Putting a Number on the Drag
Three of the figures above arrive already finished. The 0.6%, the 2% and the 25.5% are quoted from someone else’s formula, and the sentence that follows them — that a pool’s advertised yield has to beat this drag before you are actually ahead — names a threshold and never computes one. All of it is recoverable from the mechanism this article has already described, because a constant-product pool is one expression: hold two tokens in a pool while their relative price moves by a factor of r, and what you end up with is 2√r ÷ (1 + r) of what you would have had by simply holding both. Nothing below uses a token price, a protocol, or a forecast.
The Three Quoted Figures, Derived
The first thing worth doing with a formula an article cites is running it, so the page’s own three numbers are the first three this one had to reproduce before it was allowed to print anything else. They reproduce. The column beside them is the part the formula gives away for free.
| Price ratio | Loss vs. holding | Same loss at |
|---|---|---|
| 1.25x | 0.62% | 0.80x |
| 1.50x | 2.02% | 0.67x |
| 2.00x | 5.72% | 0.50x |
| 5.00x | 25.46% | 0.20x |
| 10.00x | 42.50% | 0.10x |
The expression is unchanged when r is replaced by 1 ÷ r, so the right-hand column is not an approximation — the two losses are identical to the last decimal place the arithmetic carries. A token that halves costs a liquidity provider exactly what a token that doubles costs: 5.72% either way. That is worth separating from the intuition it contradicts. Impermanent loss is usually explained, as it is above, by what happens when one token rises and traders buy it out of the pool, which invites the reading that the risk is about being on the wrong side of a winner. It is not. It is about divergence in either direction, and a provider who has talked himself into a pool on the grounds that he would be content to own more of the token if it fell has not avoided the drag at all. He has chosen the mirror row.
What the Yield Actually Has to Beat
The drag is a one-time gap measured at exit; the fees are a rate earned per day. They are not comparable until the gap is put on the same clock, and that conversion is the whole of the sentence this section leaves hanging. Asking what fee APY exactly cancels the loss turns the drag into the number a quoted yield can be held against.
| Price ratio | 30-day hold | 90-day hold | 1-year hold |
|---|---|---|---|
| 1.25x | 7.85% | 2.55% | 0.62% |
| 1.50x | 28.19% | 8.63% | 2.06% |
| 2.00x | 105% | 26.98% | 6.07% |
| 5.00x | 3,472% | 229% | 34.16% |
Read down the last column and the drag looks survivable; read across the first row of each and it does not. The same 1.5x divergence that costs 2.06% a year to outrun costs 28.19% a year to outrun if it happens inside a month — not because the loss is larger, but because there was less time to collect fees against it. The 5x row is the one that explains the shape of the advertised numbers: a move the article already describes as costing about a quarter of the position needs roughly 3,472% annualized to have been worth entering over thirty days. No sustainable fee schedule pays that, which is the point. A headline APY is a rate on the calm case and the drag is a charge on the volatile one, so the pools quoting the largest percentages are quoting them on precisely the pairs where the charge is largest. The two numbers are not competing estimates of the same thing; one is the reward for the period being quiet and the other is the bill if it is not.
Why a Stablecoin Pair Is Different in Kind
The article notes that pools of two closely-pegged assets suffer far less of this, and adds, correctly, that less is not none. Both halves of that sentence have sizes, and they are not the sizes the phrase suggests.
| Depeg | Drag | Against the 5x loss |
|---|---|---|
| 1% | 0.0013% | 1 part in 20,168 |
| 2% | 0.0051% | 1 part in 4,991 |
| 5% | 0.0329% | 1 part in 774 |
| 10% | 0.1386% | 1 part in 184 |
“Far less” turns out to be four orders of magnitude: at a one-cent gap between two dollar-stablecoins the drag is about one part in twenty thousand of what the 5x row costs, which is not a smaller version of the same risk so much as a different risk. But the rows do not fall away evenly. For small moves the loss runs as the square of the divergence, so a depeg twice as large costs almost exactly four times as much — 4.04 times, measured between the first two rows. That is what makes the second half of the article’s sentence worth keeping. The quadratic is why a stablecoin pool feels like nothing for as long as the pegs hold, and it is also why the comfort built up over a year of one-cent wobbles is not evidence about a day when one of them goes to ninety cents. The same curve produces both, and the bottom row of this table is still a peg holding better than the worst days this site’s stablecoin article records.
Method and limits, so this can be checked rather than taken on trust. No calculator on this site computes impermanent loss, so nothing above comes from a shipped tool; every figure is arithmetic on the constant-product rule this article already describes, computed in code and checked before publication, with the page’s own 0.6%, 2% and 25.5% asserted at the page’s own precision before anything else is allowed to print. Three limits are real. The model is the plain two-token constant-product pool and assumes no fees collected, no deposits or withdrawals during the period, and a provider holding the same share throughout, so it isolates the drag rather than describing any particular pool; concentrated-liquidity designs are a different arithmetic and are not covered here. The price ratio is the ratio of the two tokens to each other, not either one against the dollar, which is why the stablecoin rows are about the gap between the two pegs rather than about either coin. And the second table answers what a fee rate would have had to be, given a divergence that already happened — it is a way of sizing a quoted yield against a scenario, not a prediction that any divergence will occur, and nothing here says whether any pool is worth entering.
The Regulatory Gray Zone
Here’s a point that’s easy to read backwards. In April 2025, the US repealed the “DeFi broker rule” — an IRS regulation, finalized in December 2024, that would have required DeFi front-end services to report user transactions like a broker starting in 2027. Congress nullified it under the Congressional Review Act and the President signed the repeal on April 10, 2025 [source: RSM, Thomson Reuters, Withum tax alerts on the DeFi broker-rule repeal, April 2025]. Centralized exchanges that hold your assets and convert dollars to crypto remain subject to broker reporting (they begin issuing Form 1099-DA for 2025 activity), but purely on-chain DeFi services were carved out [source: same tax reporting].
Crypto headlines framed this as a “win” for DeFi, and for tax-reporting burden it was. But read it for what it means about protection: less reporting and less oversight is not the same as more safety for you. It means fewer eyes, fewer records, and fewer of the guardrails that exist in regulated finance. The stablecoins that DeFi runs on did get a federal framework in 2025 (the GENIUS Act — see the stablecoins article), but the DeFi protocols themselves still operate largely outside the consumer-protection regime that covers banks and brokers. The right way to hold this: DeFi’s light-touch regulatory status is a reason for more caution, not less. When something goes wrong, the thin regulation that helped it move fast is also the thin regulation that leaves you with little recourse.
What This Means for You
If you decide to touch DeFi at all, a handful of intermediate-level disciplines carry almost all the protection:
- Understand every layer you’re standing on. Composability means your money can be threaded through several protocols at once, and you inherit the risk of all of them. If you can’t explain what each block in the stack does and how it could fail, you’re not investing — you’re guessing with extra steps.
- Treat high yield as a warning light. The advertised percentage is the marketing; the risk behind it is the product. Before chasing a yield, make yourself name where it comes from and what happens to it in a crash.
- Start with battle-tested, widely-audited protocols — and still assume they can fail. Longevity and heavy scrutiny reduce the odds of a catastrophic bug; they don’t remove it. “Audited” is a starting question, not a safety certificate.
- Size it like the speculative position it is. Everything in this silo returns to the same rule from the position-sizing article: decide amounts when you’re calm, and never put into DeFi more than you can afford to see go to zero, because in DeFi zero is a live outcome with no backstop.
- Remember what you gave up. No insurance, no reversals, no support. That’s the deal you accept the moment you leave the regulated system. It can be a fair deal — for money you can genuinely afford to lose, in exchange for access and control. It is a terrible deal for money you need.
DeFi is one of the most interesting things happening in finance: an open, programmable, always-on financial system that anyone can build on and anyone can use. That openness is real, and so is its cost. The people who get hurt are almost never the ones who understood the tradeoff and sized for it — they’re the ones who heard “earn 20%” and never heard “and there’s no one to call.” Now you’ve heard both.
Where to Go Next
DeFi sits on top of everything else in this silo, so the safest path is to understand the layers underneath it first:
- How to Buy Your First Bitcoin Safely: A Step-by-Step Guide — the pillar: the risk-first walkthrough everything here plugs into.
- Crypto Wallets Explained: Hot vs Cold Storage for Beginners — the wallet you connect to a DeFi app is the door to your funds; this is how to think about that door.
- Stablecoins Explained: How They (Try To) Hold Their Peg — the “cash” almost every DeFi protocol depends on, and how it can break.
- Common Crypto Scams and How to Spot Them Before You Lose Money — rug pulls and fake protocols live here; DeFi’s permissionless openness is exactly what these exploit.
If you want markets explained plainly — risk-first, never hyped, no price targets — that’s what the newsletter is for. Subscribe below.
Disclaimer: This article is educational content, not financial advice. I am not a licensed financial advisor, and nothing here is a recommendation to buy or sell any security or asset. Investing and trading involve risk, including the possible loss of the money you invest. Do your own research and consider consulting a licensed financial professional before making investment decisions. Read the full Disclaimer.
Historical and backtested results are hypothetical, carry inherent limitations, and do not guarantee future results. Figures were accurate to the best of my knowledge as of this article’s last-updated date and may have changed.
